
What is the minimum wage in Portugal in 2026?
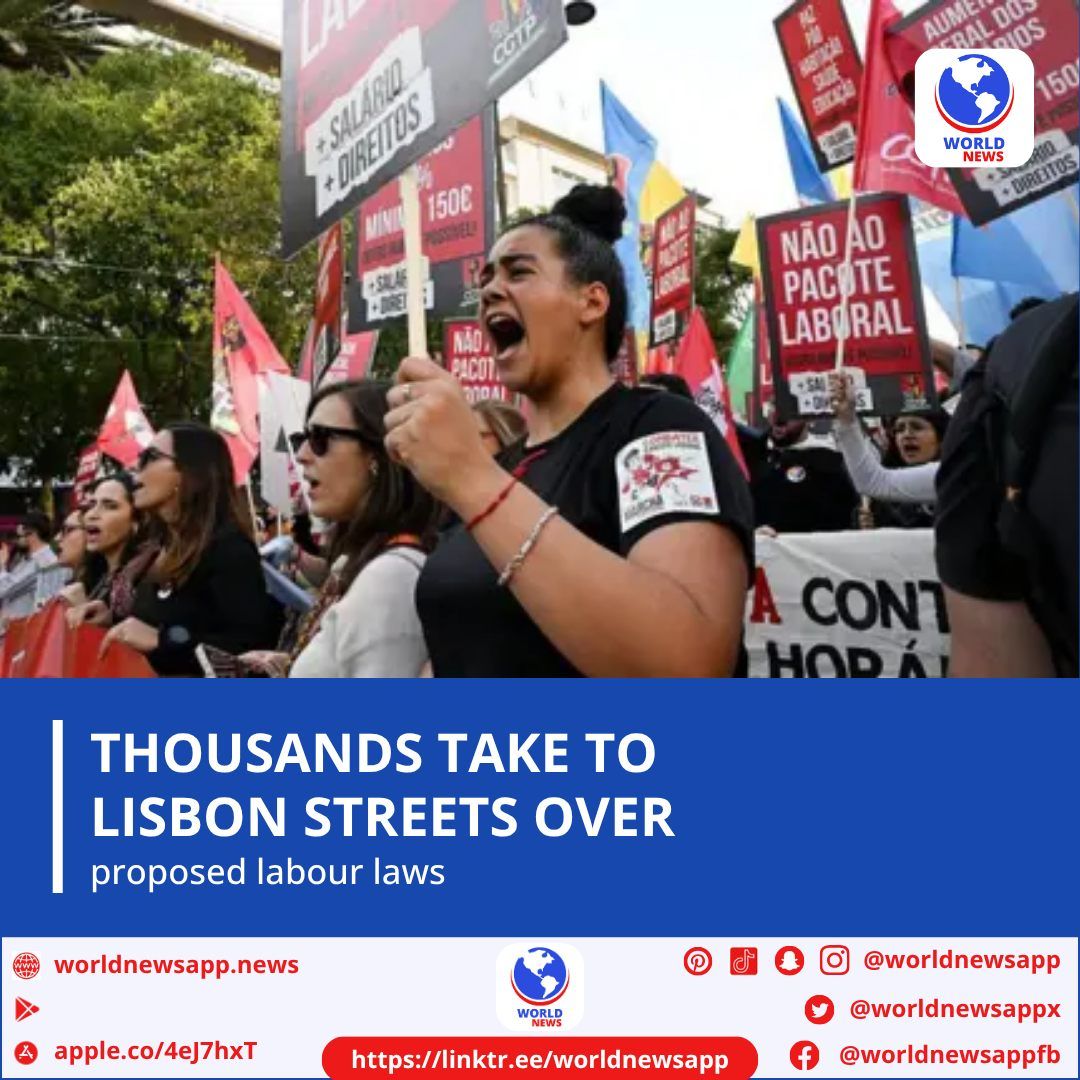
The national minimum wage (Retribuicao Minima Mensal Garantida) in Portugal for 2026 is EUR 920 per month for 14 payments, which equals EUR 12,880 per year. Portugal has been increasing the minimum wage annually as part of a government commitment to reach EUR 1,020 by 2028.
Portugal’s labor framework, housed mainly within the Codigo do Trabalho (Labor Code), emphasizes robust worker protections, mandatory social security contributions and a 14-month salary structure that substantially impacts employment costs.
Companies establishing operations in Portugal or bringing on their first Portuguese employees must grasp these rules for effective budgeting, compliance and preventing expensive disputes.
Portuguese employment law through 2026 covers here all essential aspects such as contract kinds, working hours, compensation structure, social security contributions, termination policies and the developing landscape for remote work.
For the financial impact of employment costs, see Cost of Starting a Business in Portugal. For broader compliance obligations, see Portugal Business Laws and Compliance.
Employment Contract Types
Several employment contract types exist under Portuguese law, each come with specific rules and restrictions.
Open-Ended Contract (Contrato sem Termo)
The open-ended (permanent) contract is the default and preferred form under Portuguese law. It provides the strongest protection for employees and does not have a predetermined end date. Employment continues until terminated by one of the legally permitted grounds.
Fixed-Term Contract (Contrato a Termo Certo)
Fixed-term contracts are permitted only when there is a temporary need justifying the limitation, such as:
- Replacement of an absent employee
- Seasonal activity increases
- Specific projects with defined durations
- New company startups (for the first two years of activity)
| Feature | Limit |
|---|---|
| Maximum duration | 2 years |
| Maximum renewals | 3 renewals |
| Total maximum including renewals | 2 years |
| Renewal must be | At least one-sixth of the initial duration |
Firms in their first two years may use fixed-term contracts without having to justify temporary need, giving startups flexibility they require.
Uncertain-Term Contract (Contrato a Termo Incerto)
This contract type is used when the work is temporary but the exact end date is unknown (for example, covering for an employee on long-term sick leave). The contract ends when the need ceases, subject to advance notice requirements.
Maximum duration: 4 years.
Part-Time Contracts
Part-time employment is recognized and regulated. Part-time employees are entitled to the same rights as full-time employees on a pro rata basis, including holiday and Christmas subsidies, annual leave, and social security coverage.
Temporary Agency Work
Companies can hire workers through licensed temporary employment agencies (Empresas de Trabalho Temporario). The agency is the legal employer, but the user company has obligations regarding working conditions, health and safety and equal treatment.
Fixed-term contracts are subject to strict legal limitations in Portugal, and their misuse is one of the most common sources of labor disputes.
If a fixed-term contract is renewed beyond the legal limits, does not state a valid justification, or is used in circumstances that do not genuinely require a temporary arrangement, the contract is automatically converted to an open-ended contract by operation of law. The employee then gains full permanent employment protections, including the strong dismissal protections.
Companies should work with a Portuguese employment lawyer or their certified accountant when drafting fixed-term contracts to ensure compliance with the specific justification and duration requirements.
Compensation Structure
The 14-Month System
Portuguese workers get paid 14 months of salary each year:
| Payment | When Paid | Amount |
|---|---|---|
| Monthly salary | Monthly (12 payments) | Base salary |
| Subsidio de ferias (holiday subsidy) | Before annual leave period | Equal to one month’s base salary |
| Subsidio de Natal (Christmas subsidy) | Up to December 15 | Equal to one month’s base salary |
These subsidies are mandatory in nature and cannot be waived or substituted by any other benefit. Calculated on the base monthly salary, they are subject to income tax withholding and social security contributions alike.
Subsidies can be requested for monthly installment payment (1⁄12 each month) instead of lump sums, though the employer is not required to agree.
Minimum Wage
The national minimum wage (RMMG - Retribuicao Minima Mensal Garantida) for 2026 is EUR 920 per month, set by Decreto-Lei 139⁄2025 effective January 1, 2026. This represents 14 payments, giving an annual minimum of EUR 12,880.
The 2025-2028 Acordo Tripartido commits Portugal to annual minimum wage growth, with EUR 1,020 per month by 2028 as the target. Future increases must be accounted for in employer planning for long-term staffing.
Meal Allowance
While not legally mandatory, the meal allowance (subsidio de alimentacao) is a near-universal benefit in Portugal. It is paid for each day worked and is partially or fully exempt from income tax and social security contributions depending on the payment method:
| Payment Method | Tax-Free Threshold (2026) |
|---|---|
| Cash payment | EUR 6.15/day |
| Meal card (electronic) | EUR 10.46/day |
Most employers provide the meal allowance via electronic meal card to maximize the tax-free benefit for both the company and the employee.
Overtime
Overtime is permitted subject to annual limits:
| Overtime Limit | Hours |
|---|---|
| Maximum daily overtime | 2 hours |
| Maximum annual overtime | 150 hours (may be increased to 200 by collective agreement) |
Overtime premium rates:
- First hour on a working day: 25% surcharge
- Subsequent hours on a working day: 37.5% surcharge
- Rest days and holidays: 50% surcharge
Social Security
Contribution Rates
| Contributor | Rate |
|---|---|
| Employer | 23.75% of gross salary |
| Employee | 11% of gross salary |
| Total | 34.75% of gross salary |
Social security contributions apply to all components of remuneration, including the 13th and 14th month payments, overtime and most allowances. The meal allowance paid within the tax-free limits is exempt.
Managing Directors (Gerentes/Membros de Orgaos Estatutarios)
Company managers who are also shareholders have a specific social security regime:
| Category | Employer Rate | Manager Rate |
|---|---|---|
| Gerente exercising management functions | 23.75% | 11% |
| Non-managing statutory body member (MOE regime, no management function) | 20.3% | 9.3% |
The contributory base for managers under the MOE regime is calculated based on their declared remuneration, with a minimum based on the IAS (Indexante dos Apoios Sociais).
Social security is the single largest non-salary employment cost in Portugal and is frequently underestimated by foreign companies. For an employee earning EUR 1,500 per month, the employer’s annual social security cost is EUR 1,500 x 14 months x 23.75% = EUR 4,987.50.
Combined with the two extra monthly payments, the total employer cost for a EUR 1,500/month employee is approximately EUR 25,988 per year, compared to the EUR 18,000 headline annual salary. Companies should always calculate total employment cost including social security and the 14-month structure before making hiring decisions.
Working Time
Standard Working Hours
| Parameter | Limit |
|---|---|
| Normal working period | 8 hours per day, 40 hours per week |
| Maximum daily working time (including overtime) | 10 hours |
| Minimum daily rest | 11 consecutive hours between shifts |
| Minimum weekly rest | 1 day per week (typically Sunday) |
Annual Leave
All employees are entitled to a minimum of 22 working days of annual leave per year. The leave accrues on January 1 and must be taken within that calendar year, although up to 10 days can be carried forward to the first quarter of the following year with employer agreement.
In the year of hiring, employees accrue 2 working days of leave per month of work, up to 20 days, usable after six months of employment.
Public Holidays
Portugal has 13 mandatory public holidays:
| Holiday | Date |
|---|---|
| New Year’s Day | January 1 |
| Immaculate Conception | December 8 |
| Good Friday | Variable (March/April) |
| Easter Sunday | Variable (March/April) |
| Liberty Day | April 25 |
| Labour Day | May 1 |
| Corpus Christi | Variable (May/June) |
| Portugal Day | June 10 |
| Assumption of Mary | August 15 |
| Republic Day | October 5 |
| All Saints’ Day | November 1 |
| Restoration of Independence | December 1 |
| Christmas Day | December 25 |
Additionally, each municipality has one local public holiday (feriado municipal).
Parental Leave
Portugal provides generous parental leave:
- Initial parental leave: 120 days at 100% of salary, or 150 days at 80%
- Shared parental bonus. If both parents share leave (each taking at least 30 days), leave extends to 150 days at 100% or 180 days at 80%
- Exclusive father’s leave: 28 consecutive days mandatory (7 immediately after birth + 21 within 6 weeks)
- Extended parental leave. Additional 3 months at 25% of salary (per parent)
Termination of Employment
Types of Termination
Portuguese law permits dismissal only under specific circumstances:
| Type | Grounds | Notice Required | Compensation |
|---|---|---|---|
| Just cause (justa causa) | Serious employee misconduct | No (but disciplinary process required) | None |
| Collective redundancy | Economic/market/structural reasons | 15-75 days depending on seniority | 14 days base salary + seniority payments per year of service |
| Job extinction (extincao do posto de trabalho) | Position no longer needed | 15-75 days depending on seniority | Same as collective redundancy |
| Unsuitability (inadaptacao) | Employee cannot perform role after changes | 15-75 days depending on seniority | Same as collective redundancy |
| Employee resignation | Voluntary | 30-60 days depending on seniority | None (employee pays if no notice given) |
| Mutual agreement | Both parties agree | As agreed | As agreed |
| Probation period termination | During trial period | 7-15 days | None |
Probation Period
| Contract Type | Probation Period |
|---|---|
| Open-ended contract (general) | 90 days |
| Open-ended contract (complex/senior roles) | 180 days |
| Open-ended contract (executive/director) | 240 days |
| Fixed-term contract (6+ months) | 30 days |
| Fixed-term contract (less than 6 months) | 15 days |
During the probation period, either party may terminate the contract without cause or compensation (subject to minimum notice periods for longer probation periods).
Disciplinary Dismissal Process
A just cause dismissal requires a formal disciplinary process:
- The written accusation note (nota de culpa) should document the alleged misconduct in detail.
- Delivery to the employee and the works council (if applicable)
- Employee response period (minimum 10 working days)
- Investigation and evidence gathering
- Written decision by the employer
The entire process typically takes 30 to 60 days. The employer bears the burden of proving just cause, and the standard is high. Common grounds include repeated unjustified absences, insubordination, theft, violence and disclosure of confidential information.
Portugal’s dismissal protection framework is among the most stringent in the OECD. The OECD Employment Protection Legislation index consistently ranks Portugal in the top tier for strictness of individual and collective dismissal regulation.
For foreign companies accustomed to at-will employment (as in the United States) or relatively flexible dismissal procedures (as in the United Kingdom), Portugal’s framework requires a fundamental shift in approach to workforce management.
Comprehensive employment contracts, clear performance management processes and documented HR practices are essential to manage the risk of wrongful dismissal claims.
The cost of a wrongful dismissal finding can be substantial: the court may order reinstatement of the employee with back pay for the entire period since dismissal, or alternatively, compensation of 15 to 45 days of base salary plus seniority payments per year of service.
Remote Work (Teletrabalho)
Portugal strengthened its remote work framework in 2022 and 2023 by laying down specific rights and obligations for both remote workers and employers.
Key Provisions
- Written agreement required. Remote work must be formalized in a written agreement specifying duration, schedule, equipment and expenses
- Right to request. Employees with children under 8 years old have the right to request remote work (employer can refuse with written justification)
- Equipment and expenses. All equipment and heightened expenses stemming from remote work - including internet and electricity costs - must be provided by or compensated fully by the employer.
- Right to disconnect. Employers are prohibited from contacting remote workers outside of working hours except in cases of force majeure
- Equal treatment. Remote workers have the same rights as on-site workers regarding career progression, training and working conditions
- Privacy. Employers cannot use remote monitoring systems to control employee activity in their homes
Expense Compensation
While the law requires employers to compensate additional expenses, the specific amount is typically agreed between the parties or established by collective agreement. Tax-free treatment of remote work expense compensation is available up to limits set by the Autoridade Tributaria.
Collective Bargaining
Portugal has an extensive system of collective bargaining agreements (Contratos Coletivos de Trabalho, or CCTs) that supplement the Labor Code with sector-specific provisions. Many CCTs establish:
- Higher minimum wages for the sector
- Additional benefits (seniority payments, professional development allowances)
- Specific working time arrangements
- Enhanced leave entitlements
- Classification systems for job categories and pay grades
Companies should verify whether their business activity falls under an applicable CCT, as the provisions are mandatory for employers covered by the agreement. The Boletim do Trabalho e Emprego (BTE) publishes all CCTs and extension orders.
Work Permits for Foreign Workers
EU/EEA Citizens
EU and EEA citizens have the right to work in Portugal without a work permit. They must register with the social security system and obtain a NIF but do not require authorization from immigration authorities.
Non-EU Citizens
Non-EU citizens require a work visa and residence permit. The most common routes are:
- Tech Visa. Streamlined work permit for employees of certified tech companies
- General work visa. Requires a job offer from a Portuguese employer and labor market test
- D7 Visa. For individuals with passive income (not technically a work visa, but allows self-employment)
- Digital Nomad Visa: For remote workers employed by foreign companies
For visa details, see Portugal D7 Visa and Portugal Digital Nomad Visa.
Employer Compliance Checklist
| Obligation | Frequency | Penalty for Non-Compliance |
|---|---|---|
| Written employment contract | At hire | Contract deemed open-ended; fines |
| Social security registration of employees | Within 24 hours of start | Fines EUR 200-9,600 |
| Workers’ compensation insurance | Before employee starts | Fines and personal liability |
| Monthly social security declarations (DMR) | By 10th of following month | Fines and interest |
| Withholding tax on salaries | Monthly | Personal liability of manager |
| Payment of 13th month (Christmas) | By December 15 | Fines and interest |
| Payment of 14th month (holiday) | Before annual leave | Fines and interest |
| Annual leave provision (22 days minimum) | Ongoing | Fines EUR 200-9,600 per violation |
| Work time records | Daily | Fines EUR 200-2,000 |
| Occupational health and safety | Ongoing | Fines and criminal liability |
For data protection obligations related to employee data, see Portugal Data Protection (RGPD/GDPR).
Related Corpy Resources
- Portugal business guide for a full overview of doing business in Portugal
- Business laws in Portugal for related articles on this topic
- Company formation in Portugal to explore adjacent considerations
- Corporate tax in Portugal to explore adjacent considerations
- Free zones in Portugal to explore adjacent considerations