

Can an Indian citizen form a UK Ltd without living in the UK?
Yes. UK company law imposes no residency or nationality requirement on directors or shareholders of a private limited company. An Indian resident can incorporate a UK Ltd entirely online through Companies House, own 100% of the shares and act as sole director without ever setting foot in the United Kingdom.
The United Kingdom sits at the top of the shortlist for Indian founders expanding abroad, and the reasons are historical as much as economic.
A 1.9 million strong Indian diaspora, the largest of any European country, has already built a layered ecosystem of accountants, immigration solicitors, commercial bankers and venture capital investors who understand the specifics of cross-border Indo-British business.
English is the native language, the legal system mirrors the common law framework Indian lawyers train under, and Companies House offers standard online incorporation for as little as GBP 100 in 2026, with a same-day service available for GBP 156.
For an Indian entrepreneur who has spent a career navigating the Registrar of Companies in Mumbai or the MCA portal in Delhi, the UK feels familiar in a way that Germany, France, or the Netherlands simply do not.
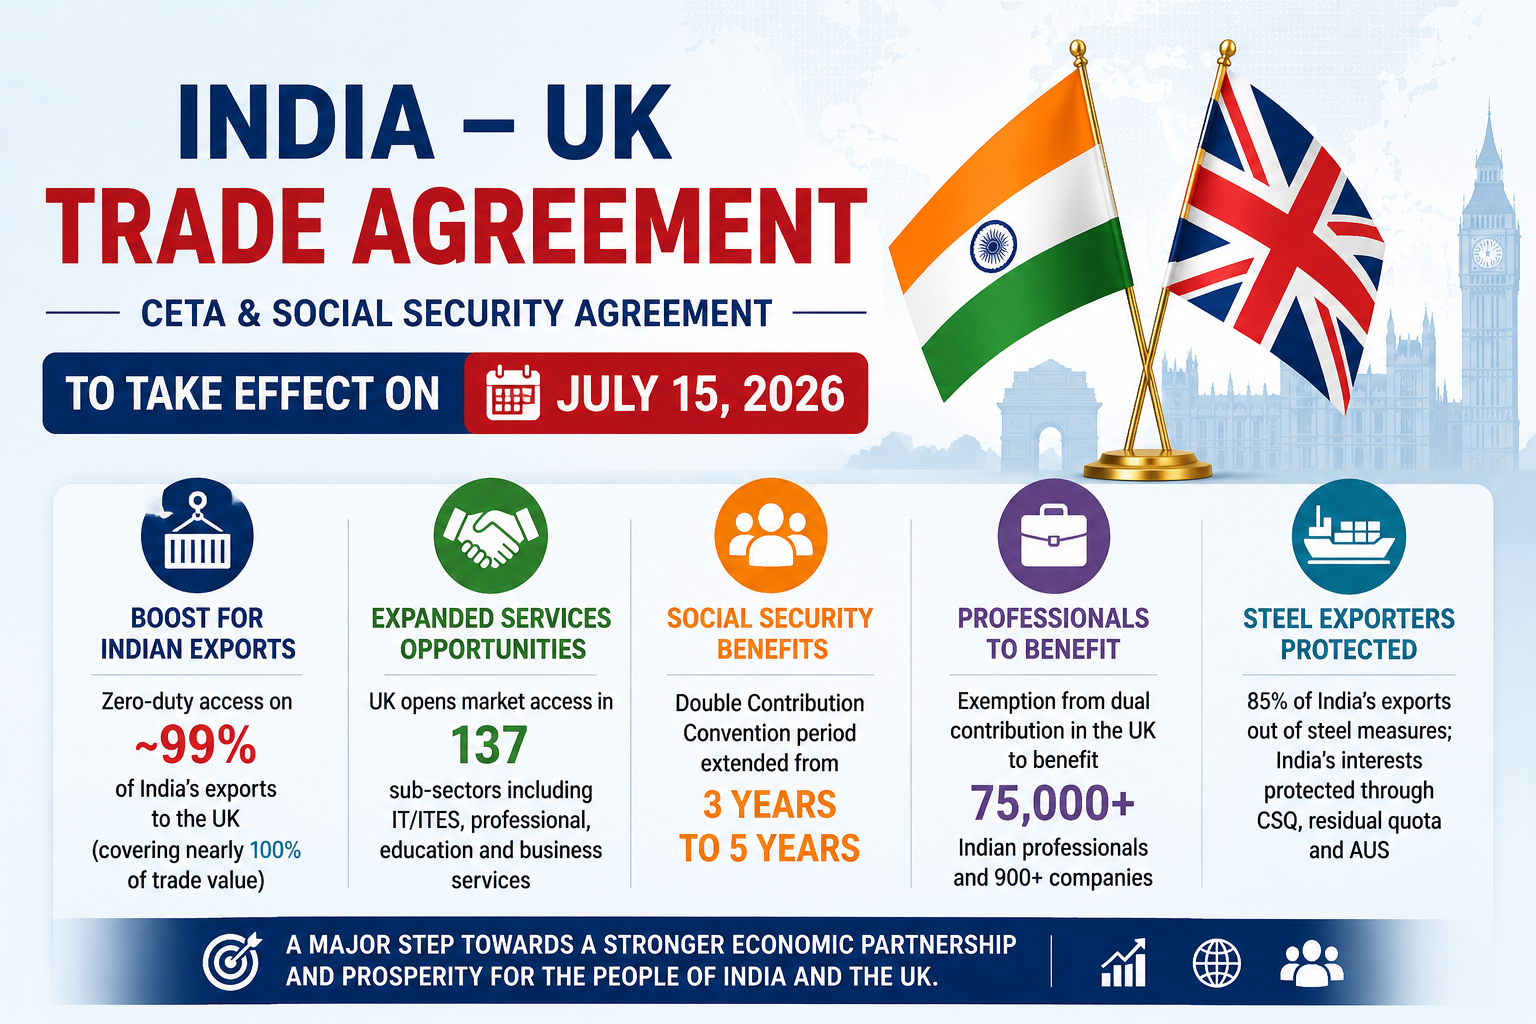
Following the India-UK Free Trade Agreement’s mid-2025 signing, which locked in tariff reductions, professional mobility quotas and the Double Contributions Convention, the commercial narrative strengthened further still.
Layer in London’s position as the largest fintech and deep-tech hub in Europe, favorable tiering in the corporation tax regime for smaller firms, and HMRC practices that are decidedly digital-first, and the UK emerges not just as a convenient jurisdiction but as a strategically important one.
This resource takes Indian founders through the visa process, structural options for companies, the actual banking environment, tax treaty arithmetic drawn from the double taxation treaty, and FEMA obligations in India that tend to receive the least attention and are often the most overlooked element of establishing a presence here.
Why UK for Indian Founders
When Indian founders establish internationally credible holding or operating companies, they evaluate four jurisdictions carefully. The UK’s strength does not come from winning on every metric, but from being rarely last on any.
| Factor | United Kingdom | United States (Delaware) | UAE (DIFC/Mainland) | Singapore |
|---|---|---|---|---|
| Incorporation speed | Same day online | 1-3 days | 2-4 weeks | 1-3 days |
| Incorporation cost | GBP 100 online | USD 300-800 | AED 15,000-50,000 | SGD 315 |
| Corporate tax | 19-25% tiered | 21% federal + state | 9% above AED 375K | 17% with rebates |
| Banking for Indian non-residents | Fintech accessible | Hard without SSN | Generally easy | Moderate, ICA needed |
| DTAA with India | Yes, 1993 updated | Yes, 1989 | Yes, 1992 | Yes, 1994 |
| Diaspora and professional network | 1.9M, deepest in Europe | 4.8M, very deep | 3.5M, largest worker base | 650K, business-dense |
| English-first regulator | Yes | Yes | Yes | Yes |
| Visa complexity | Moderate | High | Low | Moderate |
Founders selling services across Europe may find that combining a UK Ltd with a UAE or Singapore holding more efficient than the alternative structure. The UK’s treaty network, FCA payment rails and common-law system provide a premium that pure low-tax jurisdictions cannot match.
Every Indian founder does not find the UK the best option. Arabic Gulf client bases throughout the business and tax minimisation as the top objective make the UAE preferred. Venture-backed tech companies with investor desks in California make Delaware the standard choice.
For SaaS businesses targeting European corporate customers, professional services firms working with UK plc clients, fintech operations requiring credible regulatory standing or family trading businesses seeking a widely recognised international profile, the UK is nearly always the strongest bet. Read more about the jurisdiction’s fuller context at /united-kingdom.
Visa and Residency Pathway
It is critical to separate two questions that Indian founders often conflate. The first is whether you can own and run a UK company from India, which you can do with no visa at all. The second is whether you can move to the UK to build and scale that company, which is where the immigration system enters.
Innovator Founder Visa. Introduced in April 2023, this route replaced both the Start-up and the old Innovator visa. The headline change is that the previous GBP 50,000 minimum investment requirement was abolished. In its place, applicants must secure an endorsement from a Home Office approved endorsing body confirming that the business idea is innovative, viable and scalable.
The visa is granted for three years, permits secondary employment and allows application for Indefinite Leave to Remain after three years if contact point checks are satisfied.
Global Talent Visa. For Indian founders with a track record in digital technology, science, engineering, medicine, or arts and culture, the Global Talent route is frequently the faster path. Endorsement is provided by Tech Nation (for digital technology), the Royal Society, the Royal Academy of Engineering or the British Academy.
No job offer is required, there is no minimum salary and settlement is possible after three years for Exceptional Talent applicants.
Skilled Worker Visa. Holding a sponsor licence in the UK, your company can sponsor you or senior recruits from India. This route requires a genuine vacancy at or above the going salary rate for the Standard Occupational Classification code, and as of 2026 the minimum salary threshold is GBP 38,700. Five years later, settlement becomes available.
Non-resident director route. An Indian national can found and lead a UK Ltd while staying tax-resident in India. The company will be UK tax-resident by virtue of incorporation there and could also meet central management and control tests to stay UK tax-resident. The director does not owe UK personal income tax on non-UK scope work, although PAYE exposure arises from any UK workdays.
Visa options are fully detailed at /united-kingdom/visas-residency.
Indefinite Leave to Remain after five years of continuous lawful residence (three years for Innovator Founder and Global Talent) converts a business visa into a permanent status, and British citizenship follows one year after ILR. For many Indian founders, this is the real prize rather than the tax rate.
Company Structure Options
The UK offers several legal forms, but more than 95% of Indian founders choose the private company limited by shares. The table below explains why.
| Structure | Minimum capital | Liability | Tax treatment | Best for Indian founders when |
|---|---|---|---|---|
| Private Limited Company (Ltd) | GBP 1 | Limited | Corporation tax 19-25% | Default choice for trading, SaaS, services |
| Limited Liability Partnership (LLP) | None | Limited | Tax-transparent, partners taxed | Professional services, India partners taking profit shares |
| Public Limited Company (PLC) | GBP 50,000 (25% paid) | Limited | Corporation tax | Planning AIM or Main Market listing |
| Sole Trader | None | Unlimited | Income tax on founder | Rarely appropriate for non-residents |
| UK Establishment (Branch) | None | Parent liable | UK tax on UK profits only | Extending an existing Indian Pvt Ltd |
The Ltd dominates for good reasons. It ring-fences liability at the UK level, shields the Indian parent or founder from UK litigation exposure, is tax-efficient up to GBP 250,000 of profit due to the small profits rate, and carries the international credibility of a Companies House registered entity with filed accounts visible to counterparties and banks.
A Person with Significant Control (PSC) register obligation applies to every UK company. Any individual holding more than 25% of shares or voting rights, or otherwise exercising significant influence, must be registered at Companies House. For an Indian founder who is the sole shareholder, this means your name, partial date of birth, nationality and service address become public record.
Nominee arrangements do not exempt the ultimate beneficial owner from disclosure. A deeper comparison sits at /united-kingdom/company-formation.
Required Documents for Indian Nationals
One of the quiet advantages of the UK is that it does not demand apostilled documents for standard Ltd incorporation. Companies House accepts scanned copies of identity documents and a simple online declaration from the director.
Remote incorporation for Indian founders requires a focused document checklist:
- Valid Indian passport (bio page scan, colour)
- Documents showing residential address in India within the last three months are required (bank statement, utility bill, registered rental agreement).
- Checking a proposed UK company name against the Companies House register is required.
- Your primary activity should be matched using Standard Industrial Classification (SIC) codes, and up to four codes are permitted.
- Holding a registered office address in the UK is required (services ranging from paid providers starting at GBP 30 per year are available.)
- Each director requires a service address that can match the registered office.
- Memorandum and Articles of Association are required documents. Model articles are accepted by default.
- At incorporation, the standard share capital structure features one ordinary share with a nominal value of GBP 1.
- PSC declaration listing the beneficial owner
- Each director and PSC require three pieces of personal identifying information (town of birth, mother’s maiden name and passport number and if applicable, National Insurance number and telephone number).
SIC code selection deserves particular attention. Banks, HMRC and potential partners read SIC codes as a statement of intent. A software consultancy should sit under 62020, an online marketplace under 47910, a management consultancy under 70229. Misclassification at incorporation can trigger enhanced banking due diligence or complicate future VAT applications.
Step-by-Step UK Ltd Formation
- Name availability check. Search the Companies House WebCHeck to confirm the proposed name is not already in use and not too similar to an existing entity. Sensitive words (Bank, Royal, Institute, India, British) require additional permissions.
- Prepare documents and decisions. Confirm registered office provider, appoint at least one natural person director, draft share capital, identify PSCs, choose SIC codes, adopt model articles or custom articles.
- File IN01 online through Companies House. Companies House fees rose again from 1 February 2026, on top of the May 2024 increase, so figures quoted elsewhere online are frequently out of date. Standard online incorporation now costs GBP 100 (up from GBP 50 pre-May 2024) and typically returns a Certificate of Incorporation within 24 working hours. A same-day digital service is available for GBP 156 (up from GBP 78 between May 2024 and January 2026, and GBP 30 originally). Standard postal incorporation is GBP 124 and takes 8-10 working days.
- Register for Corporation Tax with HMRC. Must be done within three months of commencing trading. This triggers creation of the Unique Taxpayer Reference (UTR) which HMRC posts to the registered office within two to three weeks.
- Set up Government Gateway and enrol for online filing. This single portal handles Corporation Tax, PAYE, VAT and the annual confirmation statement. Indian directors should set up two-factor authentication using a UK or international mobile.
- Register for VAT if turnover exceeds or is expected to exceed GBP 90,000 in any rolling 12-month period. Voluntary registration below threshold is often advisable for B2B trading companies reclaiming input VAT on professional fees.
The total timeline from document collection to usable Certificate of Incorporation is typically one to three business days for online filings, the fastest of any major Commonwealth or European jurisdiction. UTR issuance adds another two to three weeks before you can file returns, and VAT registration currently runs at 30 to 40 working days at HMRC.
Banking Realities for Indian Founders
Anti money laundering rules after 2020 have added operational friction that cuts against the theoretical simplicity of UK business incorporation. Faced with remote onboarding of non-resident directors, high street banks have withdrawn aggressively. Indian founders who incorporated in 48 hours then spent four months opening an account - account access is the biggest surprise they encountered.
| Bank/Provider | Onboarding | UK-resident director needed | Monthly cost | Best for |
|---|---|---|---|---|
| Barclays Business | Branch visit usually required | Effectively yes | GBP 8-12 | Established UK presence |
| HSBC Kinetic | App-based, UK address checks | One preferred | GBP 6.50 | India-UK corridor clients |
| Lloyds Business | Branch interview | Yes in practice | GBP 8.50 | Traditional UK trading |
| NatWest Business | Branch, enhanced DD for non-res | Yes in practice | GBP 8 | SME lending relationship |
| Tide | Fully online, 48-hour approval | No | Free tier available | Fast first account, non-resident friendly |
| Starling Business | Fully online, PSD2-regulated | No, but UK proof of address may be needed | Free | Genuine banking licence, FSCS-covered |
| Monzo Business | Fully online | Residency preferred | GBP 5 | UK-based founders |
| Wise Business | Fully online, multi-currency | No | Pay-per-use | GBP/INR/USD flows, international invoicing |
| Revolut Business | Fully online | No | From GBP 10 | Multi-currency, card issuing |
The practical sequence that works for most Indian founders in 2026: open a Wise Business or Tide account within the first week after incorporation to receive funds and pay suppliers, then apply to Starling or Monzo for a fuller banking relationship.
Apply to a high-street bank only after the company has trading history, UK suppliers and ideally a UK-resident director or accountant acting as a local contact.
A complete banking map for the jurisdiction is available at /united-kingdom/banking. Expect to provide proof of UK trading activity, contracts with UK counterparties, invoices and sometimes an accountant’s letter before a tier-one bank will complete onboarding.
India-UK DTAA
The India-United Kingdom Double Taxation Avoidance Agreement, signed in 1993 and updated through protocols including the 2013 amendment, governs how business income, dividends, interest, royalties and capital gains are allocated between the two jurisdictions. For an Indian founder holding a UK Ltd, the practical numbers matter more than the treaty architecture.
Dividend withholding. Domestic UK law does not require withholding tax on outbound dividends to non-UK shareholders, making the DTAA cap of 10-15% largely theoretical when moving from UK to India. Indian tax law applies slab rates to dividends paid to an Indian resident shareholder, with no corporate tax credit for the UK corporation tax paid (section 90 relief exists only for the DTAA cap).
Interest. Depending on the lender category, the DTAA limits withholding to 10-15%. UK domestic interest withholding rates are 20% for cross-border payments, making the treaty rate operational and claimable through a Form DTTP submission to HMRC.
Royalties. The DTAA caps royalties at 10-15%. Essential for Indian founders licensing software, trademarks or content to a UK Ltd or an Indian operating company in either direction.
Capital gains. Subject to domestic law in the country of residence of the seller, with specific carve-outs for real estate rich companies. Indian residents selling shares of a UK Ltd are generally taxable only in India.
Tie-breaker. Dual residents per domestic law resolve single residence through treaty tie-breaker testing (permanent home, centre of vital interests, habitual abode, nationality, mutual agreement). The majority of Indian founders spending under 183 days in the UK continue to be taxed as Indian residents.
The Mutual Agreement Procedure (MAP) provides dispute resolution for transfer pricing adjustments and double taxation conflicts. The competent authorities on both sides are active and a queue time of 18 to 24 months is typical. Full tax implications are detailed at /united-kingdom/corporate-tax.
India-UK FTA (2025)
The India-UK Free Trade Agreement, formally titled the Comprehensive Economic and Trade Agreement, was signed in mid-2025 after more than three years of negotiation. Its relevance to a company formation guide is indirect but substantial.
Tariff reductions. Progressive elimination of duties on approximately 90% of UK exports to India, including Scotch whisky tariffs falling from 150% to 75% immediately and to 40% over a decade, automotive tariffs reducing under quota and medical device tariffs largely zero-rated. Indian exports to the UK benefit from liberalised apparel, leather, marine products and gems.
Services liberalisation. Commitments on cross-border supply and commercial presence in financial services, telecommunications, professional services and digital services. This is the chapter that most benefits UK Ltd companies run by Indian founders selling services into either market.
Professional mobility. A dedicated annex creates quotas for up to 1,800 Indian professionals per year across chefs, yoga instructors, musicians and contractual service suppliers on short-term assignments. This is additive to the Skilled Worker visa and does not replace it.
Double Contributions Convention. Indian professionals on UK assignments, and vice versa, are exempted from the host country’s social security contributions for up to three years. UK employers of Indian secondees save the 15% employer National Insurance contribution, a material saving that changes the economics of inbound secondments.
Investment protections. Fair and equitable treatment, non-discrimination and investor-state dispute settlement mechanics for qualifying investments.
The FTA does not create a shortcut to UK company formation. It does, however, shift the cost-benefit calculation for UK-India trade, making a UK Ltd sourcing from India or selling into India materially more competitive than it was in 2024.
Indian Regulatory Obligations
This is the section most Indian founders underweight and most Indian chartered accountants emphasise. Forming a UK company is simple, complying with Indian outbound rules is not.
FEMA ODI framework. Under the Foreign Exchange Management (Overseas Investment) Rules 2022 and the RBI Master Direction on Overseas Investment, a resident individual can invest abroad via the Overseas Direct Investment route in an operating entity, or via the Overseas Portfolio Investment route in a non-operating entity.
ODI in a UK Ltd where the investor has control requires Form FC filing through an AD Category-I bank before remittance.
Liberalised Remittance Scheme. Resident individuals are capped at USD 250,000 per financial year for all current and capital account transactions combined. This includes the ODI remittance, tuition fees abroad, travel and any other overseas expenditure. Exceeding the cap requires prior RBI approval.
Annual Performance Report. Every Indian resident who has made an ODI must file an APR through the AD bank by 31 December each year, disclosing the UK entity’s financials, dividends received and valuation.
Schedule FA in ITR. Indian tax residents must disclose all foreign assets including shares of the UK Ltd, foreign bank accounts, foreign beneficial interests and trusteeships in Schedule FA of the Income Tax Return. Non-disclosure carries penalties under the Black Money Act of INR 10 lakh per year regardless of tax liability.
Advance tax. Dividend income from the UK Ltd is taxable in India at slab rates and subject to advance tax in four instalments during the Indian financial year. DTAA credit for UK tax (if any) is claimed in the Indian return.
UK Corporate Tax for Indian Founders
April 2023 brought major changes to UK corporation tax. The unified 19% rate gave way to a tiered system that benefits smaller companies at the expense of larger ones. By 2026:
- Main rate. Profits above GBP 250,000 face a 25% rate.
- Small profits rate: 19% applies to profits up to GBP 50,000.
- Marginal relief applies between GBP 50,000 and GBP 250,000, producing an effective marginal rate of 26.5% in that band
Thresholds apply across associated companies - those broadly defined as firms under common control. A founder managing an Indian Pvt Ltd and a UK Ltd within 100% common control will experience the UK thresholds cut in half to GBP 25,000 and GBP 125,000.
VAT. The standard rate is 20%, the reduced rate 5% and exports and specific goods qualify for zero-rate treatment. Businesses must register when rolling taxable turnover exceeds GBP 90,000. Digital services from overseas providers to UK consumers follow specialized rules under what the UK has implemented following Brexit.
Comparison to India. Indian domestic companies pay 25% base rate (22% under the concessional regime for new manufacturing) plus surcharge and cess, bringing the effective rate to around 25-30%. The UK’s 19% small profits rate is therefore meaningfully lower, making the UK attractive for routing SME-scale profits.
Real Cost Breakdown
Approximately 1 GBP = 104 INR is the 2026 exchange rate used throughout. All numbers are indicative only and do not include professional fees for complicated restructurings.
| Item | GBP (2026) | INR equivalent | Frequency |
|---|---|---|---|
| Companies House online incorporation | 100 | 10,400 | One-off |
| Registered office service | 30-150 | 3,120-15,600 | Annual |
| Director service address | 25-80 | 2,600-8,320 | Annual |
| Confirmation statement filing fee | 50 | 5,200 | Annual |
| Accountant for year-end accounts (micro entity to trading Ltd) | 600-2,500 | 62,400-260,000 | Annual |
| VAT registration filing (professional, if applicable) | 150-350 | 15,600-36,400 | One-off |
| Corporation Tax return (CT600) | 400-900 | 41,600-93,600 | Annual |
| Business bank account (fintech) | 0-120 | 0-12,480 | Annual |
| UK director’s payroll setup (if any) | 200-500 | 20,800-52,000 | One-off |
| First-year total, non-resident director (all items above) | GBP 1,555-4,750 | INR 161,720-494,000 | First year |
Common Pitfalls Indian Founders Face
- Banking rejection. Assuming that same-day incorporation means same-week banking. Allocate four to ten weeks for a fintech account and three to six months for a high-street relationship.
- HMRC reporting burden. The combined weight of Corporation Tax return, annual accounts, confirmation statement, PAYE real-time information, VAT quarterly returns and P11D benefits returns gets severely underestimated. Penalties kick in automatically for missing any one of these.
- VAT threshold surprise. Mandatory registration occurs upon crossing GBP 90,000 of UK taxable turnover starting in the following month, registration cannot be deferred. Retroactive registration and output VAT on prior invoices create substantial burdens.
- National Insurance for UK-resident directors. When you move to the UK on a visa and pay yourself a salary, the employer contribution of 15% and employee contribution of 8% combine to make dividends substantially more tax-efficient than salary above the GBP 12,570 personal allowance.
- Confirmation statement deadline. Annual filing at the anniversary of incorporation. A day late means the company risks being struck off and the PSC public record marked delinquent, which banks check.
- FEMA ODI non-compliance. Moving equity out of India without Form FC runs afoul of FEMA rules and the RBI requires remediation for this breach. Even valid transactions result in penalties and professional fees that range INR 2-5 lakh compounded together.
- Schedule FA omission. Failing to report UK Ltd shares and related UK bank accounts in the Indian ITR constitutes a Schedule FA omission. Penalties under the Black Money Act amount to INR 10 lakh per year for this omission, irrespective of tax impact.
Verdict
Founders based in India should consider the UK jurisdiction for businesses selling professional services, software, content or financial products into English-speaking B2B markets. Firms where European customers expect a European counterparty but find EU member state requirements unattractive also benefit from UK placement.
Regulated financial work within fintech scopes and FCA standing is important, as is a corporate profile capable of passing institutional client scrutiny. Founders requiring a credible corporate image for institutional clients prefer the UK. Additionally, this jurisdiction appeals to Indian founders building toward a potential path to UK settlement and British citizenship.
The UK is the wrong jurisdiction when the business is primarily Gulf-facing and tax minimisation is the decisive factor (choose UAE), when venture capital is the only capital source and investors insist on Delaware C-Corp (choose US), when Southeast Asian expansion is the primary geography (choose Singapore), or when the founder wants a low-administration holding vehicle without trading activity (choose UAE free zone or Singapore holding).
For the sizeable middle ground of Indian entrepreneurs building internationally credible, English-speaking, moderately regulated businesses, the UK in 2026 is difficult to beat. Same-day incorporation, the small profits corporation tax rate, a deep Indian diaspora professional network, a functioning DTAA and the newly-signed India-UK FTA combine into a package that few jurisdictions can match.
The banking friction and compliance calendar are real costs, but they are known costs and they are the price of the credibility that the UK confers on the founder who undertakes them.
FAQ
Can an Indian citizen establish a UK Ltd without residing in the UK? Absolutely. No residency or nationality requirement exists for directors and shareholders of a UK private limited company. Practical challenges emerge later, chiefly at the banking onboarding phase.
Do you need FEMA/RBI clearance in India before incorporation? Affirmative if equity is being remitted from India. Under the 2022 FEMA Overseas Investment Rules, the ODI process requires your AD Category-I bank to file Form FC, with APR and Schedule FA compliance obligations that follow annually.
Innovator Founder Visa. Replacing both the Start-up and Innovator routes post-April 2023. Backed by an endorsement from a Home Office approved body attesting to innovation, feasibility and growth potential. The minimum GBP 50,000 investment requirement is gone. Settlement becomes eligible after three years.
How much does the India-UK FTA save my business? Directly, the Double Contributions Convention saves 15% employer National Insurance on Indian secondees for up to three years. Indirectly, lower tariffs and liberalised services rules reduce the cost of UK-India trade, and the professional mobility quota adds up to 1,800 specialist visa slots per year.
What is the UK corporation tax rate for a UK Ltd? 19% on profits up to GBP 50,000, 25% above GBP 250,000, marginal relief in between. Associated companies share the thresholds, so an Indian Pvt Ltd under common control halves them.
Will a UK bank open an account for a non-resident Indian director? Fintechs including Tide, Starling, Monzo, Wise Business and Revolut Business open accounts fully online. High-street banks generally require a UK-resident director or an in-person branch visit and trading history before onboarding.
Related Corpy Resources
- United Kingdom business guide for a full overview of doing business in United Kingdom
- Company formation in United Kingdom for related articles on this topic
- Corporate tax in United Kingdom to explore adjacent considerations
- Business laws in United Kingdom to explore adjacent considerations
- Free zones in United Kingdom to explore adjacent considerations
How to register a company in India for free from the UK for Indian citizens?
Registering an Indian company is not free - SPICe+ registration at Ministry of Corporate Affairs requires INR 1,000 to 10,000 (GBP 10 to 100) in government fees plus INR 300 to 500 for digital signature certificates.
Indian Private Limited Company minimum costs: GBP 10 to 100 MCA fees + GBP 3 to 5 DSC + GBP 0 to 50 name reservation + optional professional fees GBP 100 to 500 for company secretary package. For UK-based Indian citizens (including OCI holders), the cheapest path is self-service SPICe+ at around GBP 50 to 150 total. Timeline: 3 to 10 business days.
Requirements: 2 shareholders, 2 directors with at least one Indian resident (OCI card holders count, 182-day presence exemption applies to Indians returning), INR 1 lakh (GBP 950) minimum authorized capital (INR 1 paid-up acceptable), Indian registered office. UK-based Indian citizens without OCI need an Indian resident co-director.
UK Ltd for comparison: £100 via Companies House (standard online incorporation, effective 1 February 2026), 24 hours, no minimum capital, no director residency requirement.
For UK-based Indian founders targeting European markets, UK Ltd is dramatically cheaper on an ongoing basis (roughly £80 to £200/year in confirmation statement and registered office costs vs INR 50,000 to 200,000 annual compliance for Indian Pvt Ltd). Indian company registration makes sense only with actual Indian operations or market presence.
How to register a company in India online from UK?
UK-based founders register Indian companies through SPICe+ (Simplified Proforma for Incorporating Company Electronically Plus) at mca.gov.in for INR 1,000 to 10,000 (GBP 10 to 100) in government fees. Digital signature certificate (DSC) for each director and subscriber costs INR 300 to 500 each. Timeline: 3 to 10 business days.
Requirements: Indian Pvt Ltd needs at least 2 shareholders (can be foreign/UK), 2 directors (at least one Indian resident or OCI card holder with 182+ day Indian presence), INR 1 lakh minimum authorized capital (INR 1 paid-up acceptable), Indian registered office address, PAN and TAN (combined in SPICe+). UK-Indian tax treaty prevents double taxation on dividends, interest and royalties.
For UK founders targeting Indian customers, Indian Pvt Ltd opens access to GST input tax credits (GST 18% on most services), Indian domestic banking at HDFC, ICICI, SBI, Axis, Kotak (2 to 4 weeks for Indian Pvt Ltd), and GeM portal government contracts. Indian corporate tax: 22% new regime without exemptions, 25% for turnover up to INR 400 crore, 30% above.
For UK Ltd comparison (£100 formation, effective 1 February 2026, + £50 annual confirmation statement + £30 to £100 registered office), Indian Pvt Ltd carries 5 to 10x higher compliance burden. UK Ltd + GST-registered Indian partner often replaces full Indian subsidiary for service exports.
How to register a company in India online for free for Indian founders from UK?
Indian company registration is not truly free - minimum SPICe+ costs are INR 1,000 to 10,000 in government fees plus INR 300 to 500 for digital signature certificates. The cheapest self-service Indian Pvt Ltd registration is approximately INR 1,500 to 3,000 (GBP 15 to 30) total for a basic company with INR 1 lakh authorized capital.
Indian government’s Startup India scheme at startupindia.gov.in offers tax benefits (3-year income tax holiday under Section 80-IAC if recognized as DPIIT startup) but not free registration.
For UK-based Indian founders wanting low-cost setup, the comparison is: Indian Pvt Ltd approximately GBP 50 to 150 total self-service (GBP 10 to 100 MCA fees + GBP 15 to 50 DSC + GBP 20 to 50 name reservation and professional tax) vs UK Ltd via Companies House at £100 total (fee covers everything, effective 1 February 2026).
UK Ltd remains meaningfully cheaper to form than Indian Pvt Ltd and has near-zero annual compliance vs 20 to 40 hours annually for Indian Pvt Ltd.
For Indian citizens in the UK targeting Indian market access, starting with UK Ltd and selling into India via online services is often more cost-effective than forming an Indian Pvt Ltd - especially for early-stage founders where the INR 50,000 to 200,000 annual Indian compliance burden outweighs market access benefits.